Malaysia withholding tax may apply to payments made to non-residents, including foreign service providers, depending on the nature of the payment and whether the income is treated as derived from Malaysia under the Income Tax Act 1967. The Malaysian payer is responsible for withholding and remitting the tax to the Inland Revenue Board of Malaysia. Failure to comply may result in penalties and disallowed tax deductions. In certain cases, double taxation agreements may reduce the applicable withholding tax rate.
In 2017, the Inland Revenue Board Malaysia or Lembaga Hasil Dalam Negeri Malaysia (LHDN), expanded the scope of withholding tax in Malaysia to capture services performed in the e-commerce industry. This includes services performed by foreign providers outside of Malaysia. Therefore, many parties have suddenly started asking what withholding tax in Malaysia is all about.
This article explains how Malaysia’s withholding tax on service fees applies, particularly for foreign service providers operating across borders.
What is Withholding Tax (WHT) in Malaysia?
Withholding tax (WHT) is the amount withheld by the party making a payment (the payer) on income earned by a non-resident (the payee), which must then be remitted to LHDN.
In simple terms: if you’re paying a foreign vendor, you withhold a set percentage of the invoiced amount and pay it to LHDN, sending the remaining balance to your vendor.
The withholding tax in Malaysia is not new and has been in existence since the Income Tax Act 1967 (ITA), and it covers payments such as:
- Contract payment
- Interest
- Royalty
- Special classes of income: Technical fees, payment for services, rent/payment for use of movable property
- Interest (except exempt interest) paid by approved financial institutions
- Income of non-resident public entertainers
Each type of payment will have different withholding tax rates and may enjoy a preferential tax rate if there is a double tax agreement between Malaysia and the country where the non-resident (foreign party) is a tax resident. The table below details the relevant forms for different payments for the withholding tax in Malaysia.
| Payment Type | Income Tax Act 1967 | Withholding Tax Rate | Payment Form |
|---|---|---|---|
| Contract payments to non-resident | Sections 107A | 10%, 3% | CP37A |
| Interest payments to non-resident persons | Section 109, Part II, Schedule I | 15% | CP37 |
| Royalty payments to non-resident | Section 109, Part II, Schedule I | 10% | CP37 |
| Special classes of income (i.e. Technical Fees, payment for services) |
Section 109B | 10% | CP37D |
| Income of non-resident public entertainers | Section 109A | 15% | Payment memo issued by assessment branch |
Does Withholding Tax Apply to Services Rendered Outside Malaysia?
Prior to 2017, the WHT in Malaysia applied only to services rendered in Malaysia by non-local vendors. From 17 January 2017, the scope of withholding tax was expanded to cover certain payments to non-residents, including cases where services are rendered outside Malaysia, subject to how the income is characterised under Malaysian tax law.
This immediately affected many services provided by foreign providers, such as Facebook, Google Ads, Stripe, GoDaddy, etc., and the fees paid to overseas service providers.
For this publication, we will focus on two types of payments under the WHT in Malaysia:
- Royalty Income under paragraph 4(d) of the Income Tax Act 1967;
- Special classes of Income under paragraph 4A of the Income Tax Act 1967;
These two types of income usually involve services from foreign service providers.
What Counts as Royalty Income Under Malaysia Withholding Tax Rules?
As per Section 2 of the Income Tax Act 1967, royalty is defined as any sums paid as consideration for the use of, or the right to use:
- Copyrights, artistic or scientific works, patents, designs or models, plans, secret processes or formulae, trademarks, or tapes for radio or television broadcasting, motion picture films, films or video tapes or other means of reproduction, where such films or tapes have been or are to be used or reproduced in Malaysia, or other like property or rights;
- Software licences and subscription payments to purchase, use, or acquire the right to use a digital application, including where the application is later modified or distributed by the user;
- Know-how or information concerning technical, industrial, commercial or scientific knowledge, experience or skill; or
- Income derived from the alienation, sale or complete transfer of ownership of any property, know-how, or information mentioned above.
Based on the GUIDELINES ON TAXATION OF ELECTRONIC COMMERCE TRANSACTIONS released by LHDN on 13 May 2019, LHDN treats payments made to Facebook, Google and similar platforms for self-managed digital advertising as payments for the use of, or right to use, the platform and classifies them as royalty income accordingly.
What Are Special Classes of Income in Malaysia?
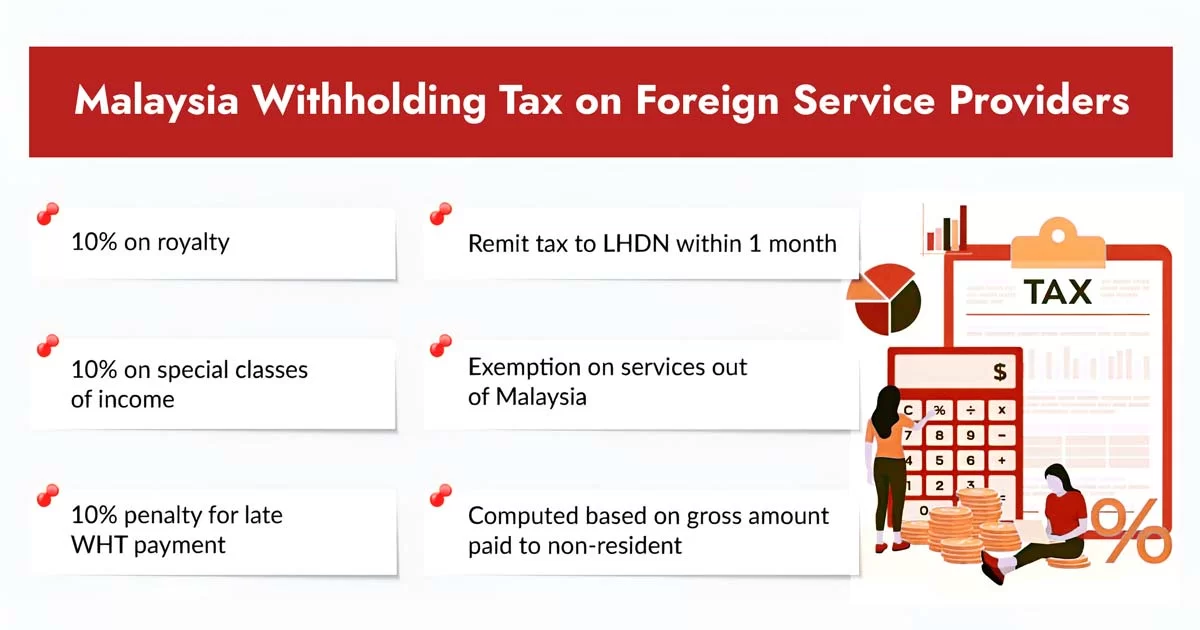
As defined under Section 4A of the Income Tax Act 1967, special classes of income refer to specific streams of income earned by a non-resident, subject to a 10% withholding tax on the gross amount where the income is derived from Malaysia, covering:
- Amounts paid in consideration of services rendered by the non-resident person or his employee in connection with:
- the use of property or rights belonging to him; or
- the installation or operation of any plant, machinery or other apparatus purchased from him [paragraph 4A(i) of the ITA];
- Amounts paid to a non-resident person in consideration of any advice given or assistance or services rendered in connection with the management or administration of any scientific, industrial or commercial undertaking, venture, project or scheme [paragraph 4A(ii) of the ITA]; or
- Rent or other payments made under any agreement or arrangement to a non-resident person for the use of any moveable property [paragraph 4A(iii) of the ITA].
This usually happens when you hire non-resident contractors to perform work for you, e.g. software development, or engage an overseas marketing agency to manage your social media marketing accounts.
Royalty Income vs Special Classes of Income in Malaysia: Key Differences
Both royalty income and special classes of income are taxed at the same domestic rate of 10%, so classification only changes the outcome once a DTA is involved, since treaties frequently set a lower rate for technical fees than for royalties. For example:
Assuming that the foreign service provider is based in Singapore, if the service is considered under Special Classes of Income (e.g., Technical Fees), it will be withheld at 5% rather than 8% (% to be withheld if it is considered as “Royalty”).
This is one of the most common areas of confusion, particularly when engaging foreign service providers across borders.
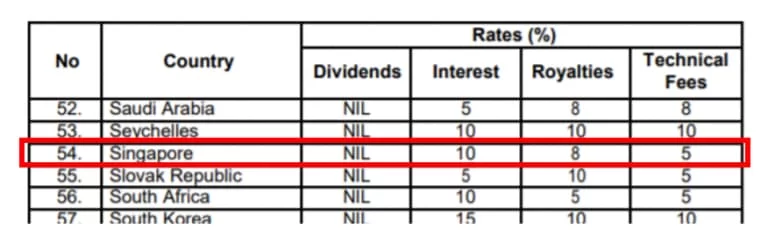
Are payments to Non-Residents in Malaysia subject to WHT under Special Classes of Income?
With effect from 6 September 2017, the Income Tax (Exemption) (No. 9) Order 2017 [P.U.(A) 323] exempts a non-resident from income tax on fees falling under Sections 4A(i) and 4A(ii) of the Income Tax Act 1967 where the services are rendered and performed outside Malaysia. Where the exemption applies, the withholding obligation under Section 109B does not arise.
Three limits apply:
- The exemption covers 4A(i) and 4A(ii) only. Rent or other payments for the use of movable property under 4A(iii) remain subject to withholding tax.
- The exemption does not extend to royalties. A payment characterised as royalty under Section 109 remains subject to 10% withholding tax regardless of where the underlying service is performed.
- Where a contract is performed partly in Malaysia and partly outside, the contract value must be reasonably apportioned.
The exemption does not change the deemed derivation rules under Section 15A. The fees remain Malaysian-sourced income and are exempted from withholding rather than removed from charge. Payers should retain documentation evidencing where the services were performed, as this is what LHDN will look for on audit.
How to Calculate Withholding Tax for Foreign Service Providers in Malaysia?
In the past, the payer was required to calculate the withholding tax in Malaysia based on the gross method.
Formula: Withholding Tax Due = (Fee Charged X Tax Rate) / 1−Tax Rate
Example:
| Fee charged by Foreign Service Provider: | RM100,000 |
| Withholding Tax: | 10% |
| Withholding Tax Due: | RM100,000 / 0.9 * 0.1 = RM11,111 |
However, with the LHDN announcement on December 5, 2018, WHT is to be computed on the gross amount paid to a non-resident.
Example:
| Fee charged by Foreign Service Provider: | RM100,000 |
| Withholding Tax: | 10% |
| Withholding Tax Due: | RM100,000 * 0.1 = RM10,000 |
Practical Examples of Withholding Tax in Malaysia
- A Malaysian company engages a Singapore-based consultant to perform services in Malaysia. Withholding tax may apply as the services are performed locally.
- A Malaysian company pays an overseas IT provider for services delivered entirely outside Malaysia. Withholding tax may not apply, depending on how the services are structured.
How Do I File and Pay Withholding Tax With LHDN?
Filing is done online through the MyTax portal or through the eTT system, where a virtual account number is preferred.
- Log in to MyTax, open ezHasil services, and select e WHT.
- Choose the form matching the payment type. CP37 for interest and royalties, CP37A for contract payments to non-resident contractors, and CP37D for special classes of income under Section 4A.
- Enter payer and payee particulars with the deduction details. Where the non-resident has no Malaysian tax reference number, one must be obtained from
- LHDN before the form can be completed.
- Save the form to generate a bill number or virtual account number. Once generated, the entry cannot be edited.
- Pay using that reference through ByrHasil, interbank GIRO, electronic funds transfer or telegraphic transfer.
- Submit the signed form and supporting documents to LHDN’s withholding tax unit as directed on the portal.
Remittance is due within one month after the date of payment or crediting to the non-resident. One month runs from that date and is not a flat thirty days, which is a common source of late remittance.
List of documents required for submitting withholding tax forms in Malaysia
- The supplier invoice or contract showing the fee and the service description
- Evidence of where the services were performed, since this determines whether the 2017 exemption applies
- The payee’s Certificate of Residence where a treaty rate has been applied
- The completed CP37, CP37A or CP37D
- The bill number or virtual account reference and the bank payment receipt
- The validated self-billed e-invoice for the transaction
What Are the Penalties for Late Withholding Tax Payments in Malaysia?
Missing the one-month deadline triggers an automatic increase of 10% on the unpaid withholding tax.
The higher cost is usually the deduction. Until the withholding tax and the increase are both settled, the underlying payment to the non-resident is disallowed in the payer’s tax computation. That adds back the full expense, not the tax. On a RM100,000 fee, chargeable income rises by RM100,000, not by the RM10,000 that should have been withheld.
There is a way back. Once the payer settles the withholding tax together with the increase, the payment to the non-resident becomes allowable as a deduction again. The increase itself is not deductible.
Claiming the deduction while the withholding tax remains unpaid carries separate exposure under Section 113(2) for an incorrect return. LHDN may also recover the unpaid tax and the increase as a debt due to the government.
Withholding tax and self-billed e-invoicing
A foreign service provider cannot issue an invoice through MyInvois. The Malaysian payer must therefore issue a self-billed e-invoice to document the transaction, using the foreign supplier’s details and the placeholder TIN code published by LHDN where no Malaysian TIN exists.
This matters for withholding tax because the validated self-billed e-invoice and the CP37 or CP37D remittance now sit in the same LHDN records. A mismatch between the value recorded in MyInvois and the amount actually withheld is visible without a separate audit trigger. Reconcile the two in the same monthly close rather than running e-invoicing and withholding tax as separate workflows.
The validated self-billed e-invoice is also the documentary evidence supporting your corporate tax deduction for the imported service. Without it, the deduction may be disallowed on audit.
What Are The Key Considerations for Businesses Engaging Foreign Service Providers?
When working with foreign vendors or regional service providers, businesses should assess:
- Whether the services are performed in Malaysia
- The applicable withholding tax rate
- Whether a double taxation agreement applies
- The responsibility for withholding and remittance
Incorrect classification may result in penalties or disallowed tax deductions during tax filing.
Understanding whether withholding tax applies is not always straightforward, particularly for cross-border service arrangements. A short discussion can help clarify your obligations and reduce the risk of misclassification or penalties.
To sum up, you must be well aware of the ongoing changes in the withholding tax in Malaysia for your business. At InCorp Malaysia, we ease your load through our comprehensive tax advisory services, or try our free corporate tax calculator now.
Please note that this publication is based on publicly available information. As tax policies may change from time to time, you may need to consider the latest tax developments when planning your withholding tax. Further, the above examples are for illustration purposes only and should not constitute tax consultation.
FAQs on Malaysia Withholding Tax
- The domestic rate is 10% of the gross payment for most service-related payments to non-residents. That covers special classes of income under Section 4A (technical and management fees), royalties, and other income under Section 4(f). Contract payments under Section 107A are withheld at 10% plus 3%. Interest and payments to non-resident public entertainers are withheld at 15%. A double taxation agreement (DTA) may reduce these rates.
- Often not. Since 6 September 2017, the Income Tax (Exemption) (No. 9) Order 2017 exempts fees under Section 4A(i) and 4A(ii) where the services are rendered and performed wholly outside Malaysia. The exemption does not cover royalties or rent for movable property under Section 4A(iii). Where a contract is performed partly in Malaysia, the fee must be apportioned. Keep documentary evidence of where the work was done.
- Usually yes. LHDN generally treats payments for the use of, or right to use, software, digital applications and self-service advertising platforms as royalties, withheld at 10% under Section 109. Because these are royalties rather than services, the 2017 offshore exemption does not apply. A DTA may reduce the rate if the provider can prove treaty residence.
- The payee must be tax resident in a country that has a DTA with Malaysia, and must provide a Certificate of Residence from that country's tax authority. With that certificate in hand, the payer withholds at the treaty rate when the payment is made. If tax was withheld at the higher domestic rate, the non-resident, not the payer, applies to LHDN for the refund.
- Within one month after paying or crediting the non-resident, whichever is earlier. Payment is made through MyTax e-WHT using the form that matches the payment type: CP37 (interest and royalties), CP37A (contract payments), CP37D (special classes of income) or CP37F (Section 4(f) income). Recurring withholding tax of up to RM500 per transaction can instead be paid half-yearly under LHDN's small-value deferment.
- The unpaid tax is automatically increased by 10%. The payment to the non-resident is also disallowed as a deduction in the payer's tax computation until the tax and the increase are paid. On a RM100,000 fee, that means RM100,000 of expense is added back, not RM10,000. LHDN can recover the unpaid amount as a debt due to the government.
Our tax professionals will navigate through the tax regulations and minimise tax liabilities for you!
About the Author